Service members buying a vehicle near a military base must verify active-duty incentive eligibility, review federal lending protections like the Servicemembers Civil Relief Act and Military Lending Act, gather essential service documentation including a Leave and Earnings Statement, and evaluate non-resident vehicle tax exemption options. Understanding these combined military benefits ensures maximum purchase savings and prevents predatory financing terms prior to signing a sales agreement.
Navigating automotive purchases while serving in the armed forces involves specialized paperwork, unique lender evaluation criteria, and distinct manufacturer discount programs. Military bases often attract surrounding commercial activity, making it vital for service members to distinguish standard retail promotions from genuine military auto incentives backed by vehicle manufacturers and federal legislation. Drivers navigating the gently rolling hills and agricultural back roads around Waynesboro benefit from heavy-duty towing capacity and high ground clearance on daily drives, making proper vehicle selection and structured financing essential for long-term ownership value.
Prior to visiting a showroom, active-duty personnel, reservists, and military retirees should confirm which documentation proves qualification for specific savings tiers. Finance departments near military installations regularly process military credit applications, but arriving with pre-gathered service records accelerates loan approvals and ensures all applicable discounts are applied directly to the contract. For personalized assistance or directions to our showroom, drivers can view our dealership address in Waynesboro or reach our sales department with a quick call.
Table of Contents
- How Do Military Car Buying Programs and Manufacturer Discounts Work?
- What Auto Loan Options and Rate Protections Apply to Military Buyers?
- What Documents Are Required to Claim Non-Resident Military Vehicle Exemption Status?
- What Should Service Members Look Out for When Buying Used Cars Near Military Bases?
- Frequently Asked Questions About Military Vehicle Purchases and Financing
- How to Claim Your Military Bonus Savings at Paul Thigpen CDJR
How Do Military Car Buying Programs and Manufacturer Discounts Work?
Military car buying programs offer direct cash allowances and specialized purchase incentives that stack on top of standard retail rebates for active-duty personnel, reserves, retirees, and recent veterans. Through programs like the Stellantis US Military Program, eligible buyers receive $500 Military Bonus Cash on select Chrysler, Dodge, Jeep, and Ram vehicles upon presenting an official third-party authorization code.
Manufacturer incentives operate by reducing the vehicle's total purchase price or capitalized cost, directly lowering the overall balance financed through the lender. Qualification extends across multiple service branches—including the Army, Navy, Air Force, Marines, Coast Guard, National Guard, Public Health Service Commissioned Corps, and NOAA Officer Corps. Eligible categories encompass active duty, active reserve, honorably discharged retirees, 100% disabled veterans, and honorably discharged veterans within 12 months of separation. Surviving spouses residing in the same household are also eligible to receive this bonus allowance with proper military dependency records.
In addition to cash allowances, manufacturers frequently offer connected vehicle discounts to active military members. For instance, qualifying buyers can access 12 months of connected navigation and safety assistance packages for the price of 10 on annual plans. Service members returning from overseas deployments can also coordinate stateside purchases in advance or explore rigorous factory-inspected models within our certified pre-owned inventory to ensure high mechanical standards and extended warranty protections upon arrival.
What Auto Loan Options and Rate Protections Apply to Military Buyers?
Service members have access to federal interest rate protections and military credit union financing options that significantly lower lifetime vehicle borrowing costs. The Servicemembers Civil Relief Act provides a 6% interest rate cap on qualifying debts incurred prior to active service, while the Military Lending Act establishes a 36% MAPR cap on covered consumer credit products for active-duty members and their dependents.
Lenders specializing in military auto loans, such as Navy Federal Credit Union, offer competitive interest rates, pre-approvals, up to 100% financing options, and extended term lengths reaching up to 96 months on new and pre-owned vehicles. Securing a pre-approval prior to shopping gives buyers a firm budget foundation and competitive leverage during contract negotiations.
Combining credit union pre-approvals with trade-in equity creates a highly favorable financing structure. When a service member applies trade equity toward a purchase, the reduced loan-to-value ratio helps secure lower interest rates and smaller monthly obligations. Buyers can begin the financing process online by submitting an online credit application and estimating vehicle trade-in equity before finalizing vehicle selection on the lot.
What Documents Are Required to Claim Non-Resident Military Vehicle Exemption Status?
Claiming non-resident military vehicle tax exemption status in Georgia requires presenting official active-duty military orders, a valid military identification card, proof of active vehicle insurance, and completed state tax affidavits. Non-resident service members stationed in Georgia can file Form PT-471 or Form PT-472NS to clarify whether they pay state sales tax or Georgia's standard 7.0% Title Ad Valorem Tax.
Under standard state regulations, Georgia assesses a one-time Title Ad Valorem Tax equal to 7.0% of the vehicle's fair market value when titling a motor vehicle. However, federal provisions under the Servicemembers Civil Relief Act protect non-resident service members stationed within the state from mandatory ad valorem property taxation. When purchasing a vehicle to title in Georgia, a non-resident service member with a home of record in another state may elect to pay standard state sales and use tax or voluntarily opt into the one-time Title Ad Valorem Tax fee if that calculation yields lower total upfront costs.
| Exemption Document / Requirement | Primary Purpose & Verification Function |
|---|---|
| Active Military Orders | Establishes active duty status in Georgia |
| Form PT-471 / Form PT-472NS | Declares non-resident tax exemption election |
| Commanding Officer Certification | Validates out-of-state home-of-record status |
| Recent Leave and Earnings Statement | Confirms active service and state tax status |
For instance, service members commuting into Augusta along the Savannah River corridor who maintain an out-of-state home of record must provide an active Leave and Earnings Statement showing state tax withholdings to establish non-resident status. Obtaining commanding officer certification on state affidavit forms ensures seamless processing at county tag offices.
What Should Service Members Look Out for When Buying Used Cars Near Military Bases?
Service members shopping for pre-owned vehicles near military bases should thoroughly inspect vehicle history reports, demand independent mechanical evaluations, and carefully audit finance contracts for hidden add-ons or inflated interest rates. Verifying baseline market value and insisting on transparent reconditioning records protects service members from overpaying or purchasing compromised vehicles.
Dealership locations surrounding military installations can vary widely in business practices. First-time military buyers should remain vigilant against high-fee add-on packages, mandatory aftermarket protection fees, and predatory subprime lending arrangements that exploit junior enlisted personnel. Reviewing the line-item breakdown on purchase agreements prevents unexpected fees from being rolled into the total amount financed.
When evaluating pre-owned trucks or SUVs, inspecting the undercarriage, brake wear, and tire condition ensures the vehicle is ready for rigorous daily service. Buyers should request a complete vehicle history report to verify past ownership records, maintenance intervals, and collision histories. Shopping through established franchised dealerships provides access to reconditioned inventory and clear pricing structures, which service members can review directly through our pre-owned vehicle inventory.
Frequently Asked Questions About Military Vehicle Purchases and Financing
Q: Is a Leave and Earnings Statement required for military auto loan approval?
Lenders standardly request a recent Leave and Earnings Statement as official proof of steady active-duty income, pay grade, and military service branch. Presenting a current LES alongside a valid military ID accelerates auto loan underwriting and helps secure competitive interest rates.
Q: Can spouses claim manufacturer military discounts on vehicle purchases?
Spouses and surviving spouses residing in the same household as eligible active-duty or retired military personnel qualify for manufacturer military bonus cash programs. Presenting active military dependent credentials or surviving spouse documentation at the dealership establishes complete program eligibility.
Q: How does a trade-in affect overall military vehicle financing?
Applied trade-in equity directly reduces the total amount financed, lowering monthly payments and reducing tax obligations in states assessing vehicle value taxes. Service members can combine trade equity with military bonus cash to minimize loan-to-value ratios.
Q: What is the difference between Military AutoSource and stateside dealership purchasing?
Military AutoSource is an authorized overseas factory-direct program for active-duty personnel stationed abroad or at sea, offering pre-negotiated pricing and stateside delivery scheduling. Stateside dealerships facilitate direct inventory delivery, immediate test drives, local trade appraisals, and regional manufacturer rebates.
Q: Are National Guard members eligible for manufacturer military incentives?
Active National Guard and Reserve personnel qualify for manufacturer incentives including the Stellantis Military Incentive Program. Proof of active reserve status via military ID or official service documentation satisfies dealership program verification requirements. Service members can explore current new Chrysler, Dodge, Jeep, and Ram vehicles to select eligible models.
How to Claim Your Military Bonus Savings at Paul Thigpen CDJR
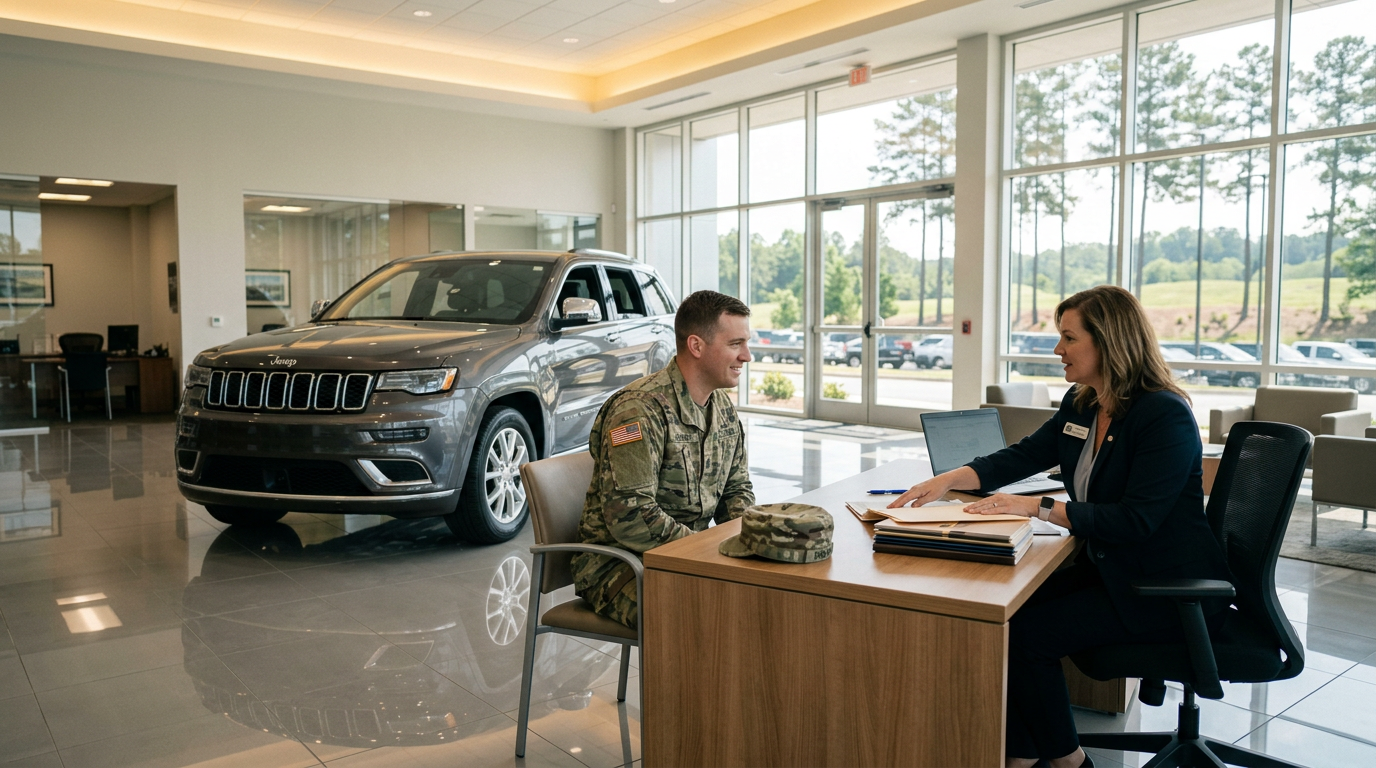
Claiming military bonus savings involves selecting an eligible Chrysler, Dodge, Jeep, or Ram vehicle, generating a verified military authorization code online, and presenting military service documentation to our finance specialists. Our team coordinates factory incentives, trade valuations, and lender discounts to maximize purchase value for military members and their families.
Service members verifying eligibility at the dealership typically present a valid military ID, recent Leave and Earnings Statement, DD Form 214 discharge paperwork, or official retirement certificate to apply bonus cash. Our finance team works directly with military personnel to compare state tax options, verify credit union pre-approvals, and ensure all applicable manufacturer allowances are credited directly to the sales agreement.
To get started, buyers can browse our online selection, arrange a test drive, or consult with our sales specialists regarding current program eligibility. You are invited to visit our dealership showroom or give our team a call at (762) 365-0910 to claim your military savings today.
Keep Your Vehicle Running Strong
Keep your vehicle performing at its best with our service team: